


You paid every premium on time. Now the insurer is stalling on the one claim that mattered.
If your insurer denied, delayed, or underpaid a legitimate California claim, whether the loss involved your home, a wildfire, a life insurance benefit, or your ability to work, you may have rights beyond the policy benefits themselves. Not every denial is bad faith. But when an insurer handles a valid claim unreasonably, California law gives you a separate legal path, and it pays to know which situation you are in before you accept whatever the adjuster offers.
The Insurance Claims We Handle Across California
Each claim type below carries its own proof, deadlines, and common insurer tactics. Start with the one closest to your situation.
Bad Faith Insurance
When an insurer denies, delays, or underpays without a reasonable basis, that conduct can be a separate legal claim from the coverage dispute itself. We evaluate whether your insurer crossed that line.
Property Damage
Earthquake, flood, water, and storm losses raise valuation and appraisal questions that go deep fast. Our Property Damage page covers that process in detail; this hub is where you start.
Fire & Wildfire Claims
Wildfire losses often involve rebuilding costs, temporary housing, and business interruption that insurers routinely undervalue in disaster-scale claim volume.
Life Insurance Claims
A wrongful denial, delay, or rescission of a life insurance benefit compounds a family's loss with a fight they should not have to have.
Disability Denial
When an insurer terminates or denies short-term or long-term disability benefits, it can leave you without income at the exact moment you depend on it most.
Every Policy Carries a Duty the Insurer Can’t Waive Away
California implies a covenant of good faith and fair dealing into every insurance policy. The insurer must give your interests at least as much weight as its own, and that duty exists independently of whether you have fully performed your own side of the contract.[1] When an insurer denies, delays, or underpays without proper cause, it can breach this separate duty, not just the contract itself, and that distinction opens the door to damages an ordinary contract claim cannot reach: emotional distress, consequential losses, and, where clear and convincing evidence shows oppression, fraud, or malice, punitive damages.[2]
Not every denial is bad faith. California recognizes a genuine dispute rule: an insurer that reasonably disputes coverage or the amount owed, after a fair investigation, is generally not liable for bad faith.[3] That is true even if a court later decides the insurer was wrong and orders it to pay. The protection has a limit, though: an insurer cannot hide behind a dispute it manufactured, an incomplete investigation, or a biased, results-driven expert.[4]
Signs Your Claim May Need a Legal Review
A single miscommunication or an honest coverage disagreement usually is not bad faith. But certain patterns are worth a second opinion:
- Your claim was denied with a vague or boilerplate explanation, not a specific policy provision.
- The insurer has gone quiet for weeks without a status update.
- An adjuster pressured you to accept an offer before you had time to assess the full loss.
- The payout does not match the estimates or documentation you submitted.
- The insurer asked for documentation far beyond what your policy requires, or asked for the same documents repeatedly.
None of these alone proves bad faith. Together, or repeated, they are the pattern a legal review is built to evaluate.
What to Preserve Before You Call
The exact documents and next steps in your case depend on your facts and your policy, but a review moves faster when you can bring:
- Your policy, declarations page, and any endorsements.
- Every piece of written correspondence with the insurer.
- The insurer’s denial letter or payment explanation.
- Any estimates or photos you have of the loss, where applicable.
- A dated timeline of what happened and when.
How Haffner Law Evaluates and Advances Your Dispute
We start by reading your policy the way a court would, not the way the adjuster’s letter suggests you should. From there, we compare the insurer’s stated reason for its decision against your policy language, your documentation, and California’s claims-handling standards, to determine whether this is a coverage dispute, a bad faith matter, or both.
If we find a viable claim, we handle the negotiation and, where necessary, the litigation directly with the insurer, so you are not doing that alone while also trying to rebuild.
Not sure if what you have is enough? ☎ Call (213) 514-5681 for a case review. We will tell you what is still needed.
Potential Recovery and California’s Insurance Claim Deadlines
The following is general information, not legal advice. Confirm your specific deadline with an attorney before relying on any of it, since exceptions and case-specific facts can change which rule applies.
- Bad faith claims: generally two years from the date of the denial or underpayment to file a bad faith tort claim (Code of Civil Procedure section 339(1)).[5]
- Property, fire, life, and disability contract claims: generally four years from the date of the breach to sue for breach of a written insurance policy (Code of Civil Procedure section 337); a separate two-year window applies if you are also pursuing a bad faith claim over the same denial (section 339(1)).[6]
- Fire and property policies specifically: can carry a much shorter deadline than the general rule above. California’s standard fire policy form generally requires suit within 12 months of the loss, sometimes extended to 24 months during a declared state of emergency, and this shorter window can override the general four-year rule.[7]
- Claims against a government-backed or public entity: generally six months for death, personal injury, or personal property loss caused by a public entity, or one year for most other claim types against a public entity (Government Code section 911.2(a)).[8]
Missing any of these windows can permanently bar recovery, so confirm which one applies to you as early as possible.
Why Californians Trust Haffner Law With Insurance Disputes
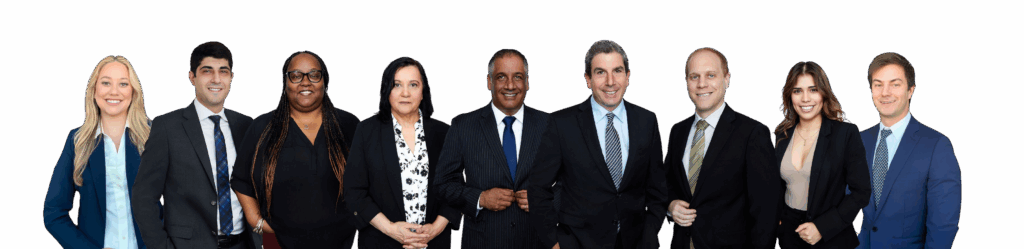
You will work with attorneys whose practice is built around insurance disputes, not generalists handling a claim on the side.
Trevor Weinberg
Trevor's insurance bad faith focus started at home: an insurer refused to pay for his own father's medical care after a disabling car crash. He later represented a family whose insurer denied a life insurance benefit over one missed payment made during the policyholder's illness. Trevor secured more than the original policy amount for them. Licensed by the State Bar of California and admitted before the Ninth Circuit, Super Lawyers named him a 2026 Rising Star.
Joshua Haffner
Joshua built his practice on insurance litigation, starting in 1997 with Northridge earthquake property-damage claims. He has argued two published insurance appeals: 21st Century Ins. Co. v. Superior Court and Doheny Park Terrace Homeowners Ass'n v. Truck Insurance Exchange. In 2012, the Consumer Attorneys of California nominated him Trial Lawyer of the Year for an insurance bad faith verdict. As founder, he leads every insurance dispute Haffner Law takes on.

Alfredo Torrijos
Alfredo, admitted to the State Bar of California in 2002, names bad faith insurance claims among his complex litigation focus. He has argued published insurance appeals, including Cordova v. 21st Century Ins. Co. and Hughes v. Progressive Direct Insurance Company. He has also brought class actions against insurers including Nationwide, Progressive, and State Farm. His technical fluency in SQL, C++, and C# helps him unpack the records and data an insurer's own systems generate.
California Insurance Claim FAQs
What counts as insurance bad faith?
Denying a valid claim without a reasonable basis, unreasonably delaying payment, undervaluing a loss, failing to investigate properly, or misrepresenting policy language to avoid paying can all qualify. A single honest mistake usually is not enough; bad faith requires the insurer to have acted without proper cause.
Does every claim denial mean my insurer acted in bad faith?
No. Insurers can lawfully deny claims that fall outside coverage or lack sufficient documentation. California also protects an insurer that reasonably disputes a claim after a fair investigation, even if a court later says the insurer was wrong. Bad faith requires an unreasonable denial, delay, or underpayment without proper cause, which is why a review looks at the specific facts rather than the outcome alone.
Can I sue the other driver's insurance company for bad faith?
Can I recover more than my policy limit?
What if my claim involves a wildfire or other disaster?
Disaster claims get the same legal protections as any other policy, but insurers are often more aggressive about minimizing payouts when thousands of claims arrive at once.
Does Haffner Law handle claims outside Los Angeles?
Yes. This page covers insurance disputes statewide across California; the deadlines and standards above are not specific to any one city.
Speak With a California Insurance Claim Lawyer
The insurer on the other side of your claim has a team built to minimize what it pays. Reach out to Haffner Law for a case review: we will examine your policy and how your claim was handled, and tell you honestly where you stand.
Call (213) 514-5681, or contact us online, or visit one of our California office locations. You pay nothing unless we win.